

Uthrive: Rewards & Cashback analysis by Appwee
Finding useful cashback is easy in theory and surprisingly easy to mishandle in practice. I approached Uthrive: Rewards & Cashback as a first-time user would: install it, understand what it is trying to do, connect it to my everyday card-reward habits, and see whether the process felt worthwhile rather than distracting. As a finance app from Uthrive.club, it focuses on helping people notice and activate available credit-card offers instead of making them search through several unrelated places.
The app is free to install, carries an Everyone age rating, and has reached over 10K installs. Its average is 4.2 from more than 281 ratings, which suggests a generally positive reception while still leaving room for the occasional rough edge. The current release is version 2.3.7, and it runs on Android 6.0 or later. There are optional in-app purchases ranging from ten cents to $69.99 per item, so I would still review any payment screen carefully before confirming anything.
Getting from installation to a useful reward
What to expect when you open it
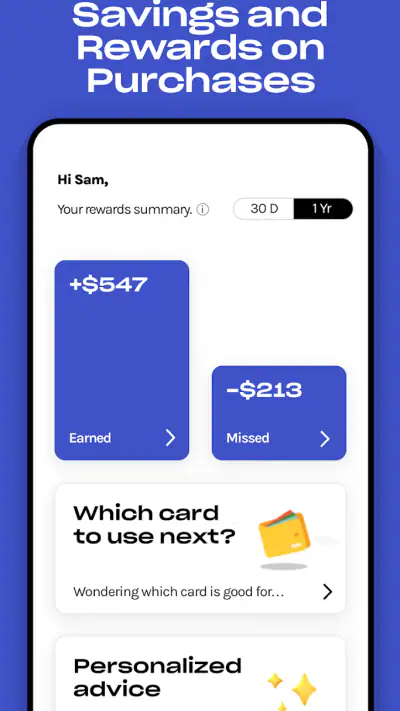
The central idea is straightforward: Uthrive looks for ways to improve the rewards you can get from cards you already use. Rather than treating cashback as a separate shopping destination, it is built around the moment when you are deciding which card or offer makes the most sense for a purchase. That distinction matters. This is not a budgeting app where the main task is categorizing expenses, and it is not simply a directory of coupon codes.
The store summary presents the possibility of unlocking over $400 in cashback, while the practical value will depend on your cards, the offers available to you, and whether you remember to use the right offer at the right time. I would treat that headline as an upper opportunity rather than a promise. The strongest use case is someone who already has one or more rewards cards but often forgets which benefits are available.
On first launch, I would keep expectations modest. The app can make reward discovery more convenient, but it cannot turn an unsuitable purchase into a good financial decision. If an offer encourages you to spend more than planned, the cashback is not really a saving. My preferred approach is to start with normal purchases—groceries, transport, meals, or a planned online order—and use the app to check whether an existing offer can improve something I was going to buy anyway.
The first setup should be deliberate
The setup stage deserves more attention than it may seem to. Finance apps often ask users to move quickly through connection screens, but I recommend reading each one and checking exactly what you are authorizing. Use an email address and account details you are comfortable using for a rewards service, and avoid treating every permission or connection prompt as a formality.
When adding a card or account, choose the cards you actually use. Adding every card you own may sound efficient, but it can make later recommendations harder to interpret. A smaller, accurate starting set gives you a clearer picture of which rewards are relevant. I would begin with the primary card used for routine spending, then add another only after the first workflow feels clear.
There is also a useful habit here that is easy to miss: keep the app aligned with your real wallet. If you stop using a card, replace it, or change the card you normally use for a category, revisit the setup. Reward tools become less helpful when their information reflects an old spending pattern. That maintenance is not exciting, but it prevents the app from suggesting an option you would not actually choose at checkout.
Because this is a finance-focused service, I would also avoid installing it solely for a one-time purchase and then forgetting about the account. The better fit is a light recurring routine: check available opportunities before planned spending, confirm the offer terms, and remove or ignore anything that no longer matches your habits. That turns the app into a decision aid instead of another source of notifications.
Your first meaningful action
The first success should not be chasing the biggest-looking reward. It should be completing one ordinary purchase with a clear understanding of why you selected a particular offer or card. For example, imagine that I am ordering household supplies I had already budgeted for. I would open Uthrive before paying, review the available cashback choices, check whether the merchant and card conditions match, and then complete the purchase through the required path.
That last check is important. Cashback systems can involve activation steps, eligible merchants, qualifying cards, purchase windows, or minimum conditions. I would never assume that merely seeing an offer means it is already active or guaranteed. If the app presents an activation control, use it before the transaction. If the offer wording is unclear, I would rather skip it than make a purchase purely because the reward looks attractive.
A practical first-session test is to ask three questions: is this offer for a purchase I already intended to make, is the card or payment method eligible, and do I understand what action records the reward? If the answer to all three is yes, the app has done something useful even before a large payout appears. It has reduced the chance that I overlook a benefit already connected to my spending.
After the transaction, keep the receipt or confirmation until the reward is reflected according to the offer’s terms. This is one of the most useful habits for any cashback service. It gives you a reference if the purchase does not track correctly and helps separate a genuine app problem from a transaction that simply did not meet the conditions.
Where new users can become confused
The biggest possible misunderstanding is treating cashback as an instant discount at checkout. In my view, Uthrive is better understood as a layer that helps activate or identify rewards; it should not be confused with an automatic reduction in the price shown by a retailer. The amount, timing, and eligibility of a reward can depend on the particular offer and the way the purchase is completed.
Another point of confusion is the difference between a card’s normal rewards and a special offer. A credit card may already earn points or cashback on a purchase, while Uthrive may highlight an additional opportunity. Those benefits are not necessarily interchangeable, and the best choice may depend on the card’s standard earning rate, the offer conditions, and whether you value simplicity more than a potentially higher return.
I would also be cautious with the word “automatic.” Automatic activation can save time, but it does not remove the need to understand the offer. Automation is helpful when it prevents forgotten steps; it is less helpful when it makes you feel that every purchase is covered without checking the details. Before paying, I would still verify the merchant, the selected card, and any qualification requirement shown in the app.
Notifications can create a second kind of friction. A reward alert may be useful before a planned purchase, but repeated prompts can make a finance tool feel like a shopping tool. If the app’s reminders begin influencing what you buy, I would reduce them or change my routine. Cashback should follow your spending plan, not write it for you.
How it compares with familiar alternatives
Compared with a bank’s own rewards dashboard, Uthrive can be more convenient for someone who uses several cards and wants a single place to think about opportunities. A bank app usually explains that institution’s card benefits well, but it may not help you compare the practical choice across a mixed wallet. Uthrive’s appeal is the attempt to make that comparison less scattered.
Compared with browser coupon extensions or general cashback portals, this app feels more relevant to people whose main interest is card-linked rewards rather than hunting for a discount code. A coupon service may be better when I am searching for the lowest retailer price, while Uthrive is more useful when I am deciding how to pay for a purchase I have already selected. The two approaches can complement each other, but neither replaces the other.
A spreadsheet or notes app remains a reasonable alternative for a very organized user. Someone with one card, few offers, and a strong memory may not gain enough from another finance app. In that situation, manual tracking can be simpler and avoids the work of maintaining another account. Uthrive earns its place when the convenience of surfacing opportunities outweighs the effort of setup and occasional checking.
Small workflows that make the app more useful
My first recommended workflow is a pre-purchase pause. Before paying for a planned online order, check Uthrive and compare the available reward with the card’s usual benefits. Do this before the checkout is complete, not afterward. This simple timing change is more valuable than opening the app randomly because it connects the information to a decision you can still change.
My second tip is to separate “available” from “worth using.” An offer can be technically eligible but still unattractive if it requires extra spending, a different card, or a purchase you would not otherwise make. I would keep a short mental rule: never buy something solely to unlock cashback unless the purchase was already justified by your budget.
A third useful workflow is to review the app before recurring expenses. Bills, subscriptions, and routine household orders are easier to plan than impulse purchases. If an eligible opportunity appears, I can activate it in advance and keep the confirmation. If nothing useful appears, I have lost only a brief check rather than spending time browsing every offer.
Finally, I would compare the reward with the card’s wider value. A card may offer travel benefits, purchase protection, or a better base rate even when a separate cashback offer looks tempting. Uthrive can help surface an opportunity, but the final decision should include the whole card relationship, not just the most visible percentage or reward amount.
Who should use it and who should skip it
I think Uthrive is a good match for people who have several credit cards, regularly forget to activate offers, or want a more focused way to review cashback before planned purchases. It is also useful for someone who dislikes searching through multiple bank apps and retailer pages. The free entry point makes it reasonable to test, provided you are comfortable reviewing account connections and optional purchase screens carefully.
I would skip it if you are trying to control impulsive spending and tend to interpret reward alerts as invitations to shop. I would also hesitate if you rarely use credit cards, prefer a completely manual system, or are unwilling to read eligibility details. The app cannot compensate for a payment habit that is already costing more in interest or unnecessary purchases than any reward could return.
People who need detailed budgeting, debt payoff planning, investment analysis, or full financial planning should look elsewhere for those specific jobs. Uthrive’s role is narrower. Its value comes from reward awareness and cashback workflow, not from replacing every financial tool on your phone.
What I would do after the first successful reward
Once the first purchase has gone through properly, I would not immediately add every possible card or chase every offer. I would review what happened: was activation clear, did I use the correct payment method, and did the reward appear as expected under the applicable conditions? That short review tells me whether the app fits my routine.
If it does, the next step is to make it part of a weekly spending check rather than a constant distraction. I would scan it before planned purchases, keep records for transactions that matter, and periodically remove cards or habits that are no longer relevant. The goal is a repeatable process that takes little attention while preventing missed opportunities.
I would also keep an eye on any optional in-app purchase prompt. The app is free, but individual purchases can range from ten cents to $69.99. That does not automatically make them unsuitable, yet it does mean I would compare the cost with the realistic reward I expect to receive and confirm the purchase deliberately instead of tapping through quickly.
After using it this way, my opinion is positive but measured. Uthrive: Rewards & Cashback is most convincing as a reminder and organization layer for card rewards, not as a reason to spend more. It can make a neglected benefit easier to notice, especially for people managing more than one card, but its success depends on careful setup and sensible purchasing decisions.
For a first-time user, the safest path is simple: add only the cards you genuinely use, test one planned purchase, read the offer conditions, save the transaction confirmation, and judge the app by whether it makes an existing habit easier. If that first experience feels clear, Uthrive.club has built a useful finance companion for your routine. If it creates more shopping pressure or complexity than value, your bank’s own rewards page or a small manual tracker may be the better choice.
Gallery
Uthrive: Rewards & Cashback Pros and Cons
- Earn cashback and rewards from eligible purchases.
- Simple interface makes offers easy to browse and use.
- Useful for users who regularly shop through partner brands.
- Rewards can add value to purchases you already planned to make.
- Promotional offers may include discounts beyond standard cashback.
- Cashback availability depends on participating merchants and current offers.
- Some rewards may require minimum thresholds before redemption.
- Tracking purchases can take time and may not update immediately.
- Terms
- exclusions
- and expiration dates vary between promotions.
- Savings may be limited if your preferred stores are not supported.
Uthrive: Rewards & Cashback Frequently Asked Questions
What is Uthrive: Rewards & Cashback, and how does it work?
Uthrive: Rewards & Cashback is a rewards app designed to help users earn benefits from eligible shopping and everyday purchases. After creating an account, you can browse available offers, activate qualifying deals, and complete purchases according to each promotion’s terms. Rewards may appear as cashback, points, or other incentives, so it is important to check the offer details, participating retailers, and tracking requirements before buying.
How can I earn cashback or rewards with Uthrive?
To earn rewards, open the app and review the currently available offers before making a purchase. Some promotions may require you to activate an offer, shop through a specific link, use a supported payment method, or meet a minimum spending amount. Tracking is not always immediate, and rewards can depend on retailer confirmation. Keep receipts and review the terms if a transaction does not appear correctly.
Is Uthrive: Rewards & Cashback free to download and use?
The app can generally be downloaded without an upfront purchase price, but users should still review the current listing and in-app information for any optional services, membership conditions, or other charges. Cashback programs may also involve eligibility rules, exclusions, minimum redemption thresholds, or expiration dates. Before committing to an offer, read the complete terms so the expected reward and any limitations are clear.
When can I redeem my Uthrive rewards, and what should I know about withdrawals?
Redemption availability depends on the type of reward, your account status, the retailer’s confirmation, and any minimum balance requirement. Some transactions may remain pending while they are verified, and rewards can be declined if an offer’s conditions were not followed. Uthrive may provide one or more redemption methods, but options, processing times, and eligibility can change, so check the app before planning a withdrawal.
Is Uthrive safe to use, and what personal information does it require?
As with any cashback service, use Uthrive only after reviewing its privacy policy, permissions, and account requirements. The app may request information needed to create an account, personalize offers, verify transactions, or process rewards. Avoid sharing unnecessary sensitive details, use a strong unique password, and download the application only from an official app store. Also check reviews and updates for current security information.














